Best Digital Debt Collection Platform for Lenders
Beyond Omnichannel Collections
A Better Way to Collect
Author
- November 18, 2026
Best digital debt collection platforms help lenders reach customers, prompt action, and track outcomes across the recovery cycle.
Banks and lenders often use SMS, WhatsApp, calls, and other channels to manage collections. While omnichannel communication adds more ways to send a message, it does not give the borrower a trusted place to act. The gaps below show why more outreach does not always lead to better collection outcomes:
1
Spam filters block up to 70% of collection calls before the phone ever rings.
2
Right Party Contact has dropped below 25%, cutting off direct engagement.
3
Nearly 30% of delinquent borrowers swap SIMs or numbers within seven days.
4
Borrowers avoid payment links sent via SMS or chat apps due to fraud concerns.
Did you know?
Trust remains a key challenge in digital finance. The World Bank highlights fraud and data misuse as major consumer risks, reinforcing why collection communication needs to come from a source customers recognize.
That’s why lenders need a digital debt collection platform that builds trust into collection communication, gives customers a clear next step, and tracks whether it leads to payment or a commitment.
[Also Read: Omnichannel Marketing Challenges and Solutions for Banks]
Key Capabilities to Look for in a Digital Collection Platform
When evaluating a platform, lenders should ask these five questions:
Does the communication stack drive action?
A platform should engage borrowers in context through voice, video, images, and text, and connect each interaction to a meaningful next step, not just record delivery or opens.
This is where TrueDigi helps. Its SDK is embedded in the lender’s app, enabling communication through voice, video, images, and text in a familiar environment. Borrowers can see what is due and take the next step, while lenders can connect engagement with meaningful action, not just track delivery or opens.
[Also Read: Is Your Debt Recovery Rate Low Despite Sending Regular Reminders?]
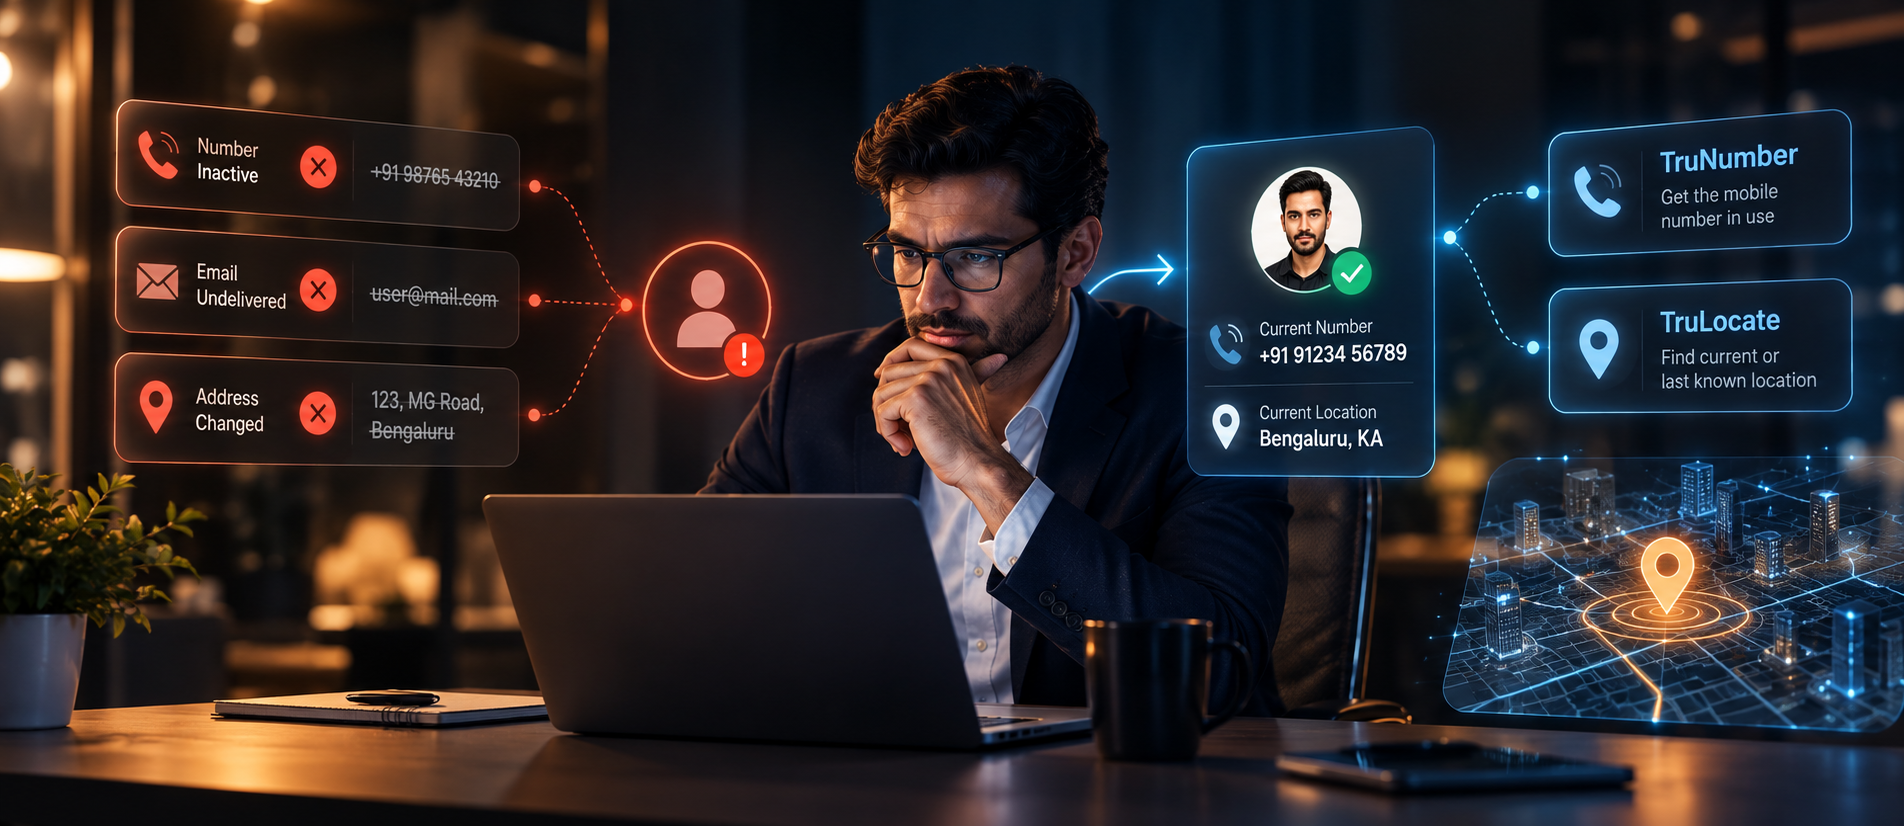
Does it provide an alternative way to reach customers if their phone numbers or SIMs change?
A platform should maintain contact through the customer’s active device, even if their phone number or SIM changes. This reduces reliance on contact details that may become outdated.
TrueDigi enables 100% Right Party Contact (RPC) by bypassing phone numbers and connecting directly to the borrower’s enrolled device. Its TruCall feature adds verified, branded outreach, driving up to 5X higher engagement than auto dialers.
[Also Read: How a Leading Financial Institution in South Asia Achieved 5X Higher Right Party Contact Rate With TrueDigi’s TruCall]
Does it give customers a clear path to resolve what they owe?
A platform should make it easy for customers to see what is due and act immediately. This may include reviewing payment options, setting a commitment date, or paying directly inside the lender’s app.
This is possible with TrueDigi’s TruPromise. It lets them commit to a new payment date in a simple and empathetic way in the lender’s app. Each commitment is recorded, timestamped, and tracked for follow-up.
Does it protect borrower data and support compliance?
A platform should protect personal customer data and support compliance with relevant standards.
TrueDigi operates strictly using unique ClientIDs. The borrower’s personally identifiable information (PII), such as name, national ID, or phone number, never leaves the lender’s secure environment, ensuring compliance with GDPR and SOC 2.
Does it support verifiable late-stage escalation?
A platform should help lenders deliver legal notices digitally and maintain a reliable record of notice delivery and customer responses.
TruNotice supports late-stage escalation by delivering legal notices to the borrower’s device and recording delivery, read receipts, timestamps, and customer acknowledgements.
Smart pick for you...
- All Posts
How satisfied are you with your current contact efficiency and RPC rates?
Based on what you've read, do you think TrueDigi can improve your outcomes?
Noted! Let's discuss further
Contact usFollow Us On
Conclusion
Now you know what to look for in a digital debt collection platform. The real question is whether your current approach is helping customers move from receiving a collection message to taking a meaningful next step. TrueDigi is not another channel in the omnichannel stack; it offers lenders a different way to connect collection communication with action.
About TrueDigi
TrueDigi is Datacultr’s AI-powered, user-trusted, direct to device customer engagement and debt recovery platform for banks and lenders. Embedded within the bank’s mobile app, it enables end-to-end journeys across collections and customer lifecycle use cases with 100% contactability, actionability, and real-time measurability.
See how TrueDigi could fit your recovery journey.
People also ask
Can a digital debt collection platform work with a lender’s existing systems?
Yes. Many platforms connect to core banking, loan management, CRM, or collections systems through APIs. TrueDigi is designed to integrate with a lender’s existing app and systems, so teams can build digital collection journeys around their current workflows.
How does TrueDigi’s AI improve debt collection?
AI analyzes borrower behavior to determine the best time, channel, and message to prompt payment. Instead of treating every customer the same, platforms like TrueDigi use AI to distinguish between borrowers who simply forgot and those who need flexible repayment plans, lifting resolution rates without manual agent effort.
How is TrueDigi different from omnichannel communication?
Omnichannel tools only add channels and measure delivery. Whereas TrueDigi works inside the lender’s app, sends voice, video, image, or text based on borrower context, and ties each message to an outcome like a payment or a promise to pay. It shifts debt collections from more outreach to better engagement.
Can TrueDigi’s digital collection platform work alongside an existing recovery team?
Yes. TrueDigi acts as a force multiplier rather than a replacement. It automates routine outreach, reminders, and self-service repayments for early-stage delinquencies, so internal agents can focus on complex, high-risk, or late-stage accounts without added headcount.



