Is Your Debt Recovery Rate Low Despite Sending Regular Reminders?
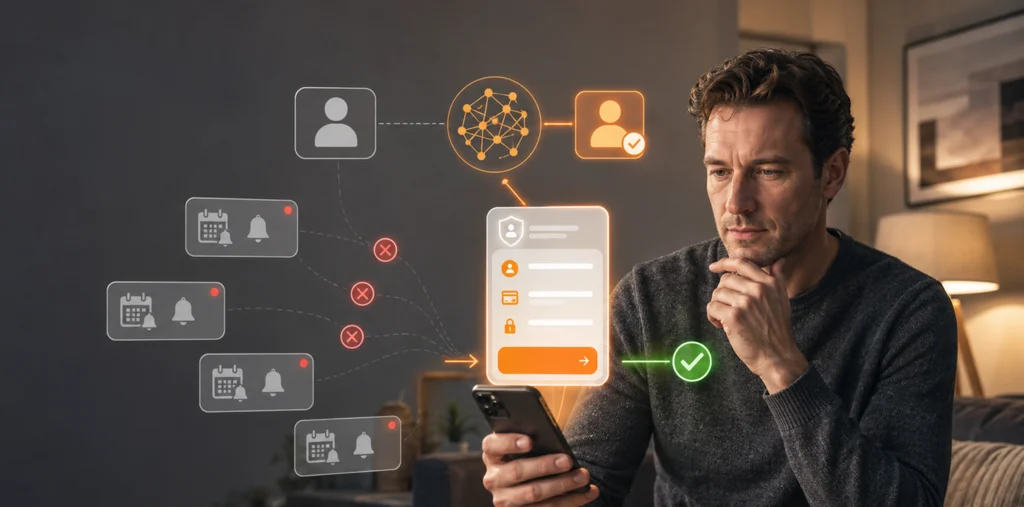
Is Your Debt Recovery Rate Low Despite Sending Regular Reminders? Payment Due. Response Missing. Make Every Message Actionable. Author Ekta Singh Published on September 7, 2026 How many reminders does it take to improve the debt recovery rate after a missed payment? One? Three? Five? Ten? A higher debt recovery rate does not necessarily require more reminders. It requires communication that reaches the right borrower, captures attention, reflects their circumstances, and makes repayment easy. A 2026 study found that 86% of calls from unknown numbers go unanswered. This reveals a fundamental problem for banks: a repayment reminder cannot influence borrower action if the communication is ignored before the bank can even identify itself. Even successful delivery does not mean progress. Banks must measure what happens throughout the recovery journey: Sent → Delivered → Viewed → Acted On → Payment Completed The real question, therefore, is not simply, “How regularly are reminders being sent?” Banks must ask: Did the reminder reach the right borrower through the right medium, and what happened next? The point where borrowers leave this journey reveals what needs to change. What Keeps the Debt Recovery Rate Low and How Can Banks Improve It? A debt recovery rate can remain low because sending a reminder does not guarantee that the right borrower receives, trusts, notices, or acts on it. Poor timing, outdated contact details, generic messages, and unclear payment steps can turn reminders into background noise. 01 Poor Right Party Contact Phone numbers, email addresses, and customer records change. A reminder may be marked as delivered without reaching the person responsible for the account. Improving right party contact requires banks to know whether communication reached the intended borrower, not simply whether a channel accepted the message. That’s where TrueDigi helps. It delivers repayment communication through the bank’s app on the customer’s device, helping banks reach the right customer before moving forward with recovery. 02 Communication Looks Like Spam or Fraud Would you answer an unfamiliar call or open an unexpected payment link? Even genuine communication may be ignored when borrowers cannot clearly identify the bank. Repeated messages through channels that look like spam or fraud may increase contact attempts without improving the debt recovery rate. Therefore, banks need a way to make urgent repayment communication easy to identify and trust. With TruAlert by TrueDigi, they can deliver these messages through their own app on the intended device. 03 Communication Does Not Match Borrower Preferences A forgotten due date, failed payment, and repeated non-payment require different responses. Borrowers may also respond differently depending on the language, communication format, and time of contact. To address this, TrueDigi uses AI to communicate in the borrower’s preferred language and channel at the right time. Messages and follow-ups can be tailored to the borrower’s previous response and collection stage, making communication more relevant. This helps banks address the engagement gaps that can keep the debt recovery rate low. [Also Read: TrueDigi by Datacultr: Turning Low Efficiency into High Collection Performance] 04 Reminder Does Not Provide a Clear Payment Action “Your payment is overdue” states the problem but does not help the borrower resolve it. A recovery-focused reminder should let the borrower: Check the amount due and payment deadline Pay securely through an authenticated payment link Report a payment issue or request support With TruEngage by TrueDigi, borrowers can review payment details and take the required action directly from the message. This turns the reminder into a clear next step instead of another general warning. 05 Borrowers Cannot Record a Promise to Pay Some borrowers intend to pay but cannot complete the payment immediately. Repeated reminders do not capture that intent or tell the bank when payment can be expected. In such cases, TruPromise by TrueDigi allows borrowers to select and confirm a promise-to-pay date and record their commitment digitally. Banks can then follow up based on whether the borrower makes or misses the promised payment. Smart pick for you… All Posts August 20, 2026 More Outreach. Same Losses? Customer Engagement Tools for Better Debt Collection July 27, 2026 Right Party Contact (RPC): Higher Collections Start With the Right Customer July 15, 2026 Debt Collection in Banking: Why Digital Notices Are Becoming Critical Follow Us On LinkedIn Improve the Debt Recovery Rate by Making Every Reminder Actionable Improving the debt recovery rate begins with asking a simple question before sending another reminder: What should this borrower be able to do after receiving it? If the answer is unclear, the reminder is incomplete. Every communication should create a measurable borrower response that helps the bank determine the next appropriate collection action. About TrueDigi TrueDigi is Datacultr’s AI-powered, user-trusted, direct to device customer engagement and debt recovery platform for banks and lenders. Embedded within the bank’s mobile app, it enables end-to-end journeys across collections and customer lifecycle use cases with 100% contactability, actionability, and real-time measurability. Turn every repayment reminder into a clear, measurable action with TrueDigi. Book a Demo People also ask Still have questions? Can’t find answers to your questions? Contact Us What Makes TrueDigi One of the Top Rated AI-Powered Debt Recovery Services? When comparing top rated AI-powered debt recovery services, banks should look beyond automated messaging. Platforms like TrueDigi offer initial reminders, interactive repayment journeys, digital promises to pay, voice communication, formal notices, and contact discovery as an account progresses through collections. How Often Should Debt Recovery Reminders Be Sent? There is no universal frequency. Banks should base timing on the repayment stage, previous responses, borrower behaviour, and applicable regulations. Repeating an ineffective reminder more frequently is unlikely to improve recovery rates. Which Metrics Should Be Tracked Alongside Recovery Rates? Banks should track right party contact, message views, borrower responses, payment actions, promises to pay, fulfilled promises, completed payments, time to resolution, and collection cost. Together, these metrics show where the debt recovery journey is working or breaking. Why Do Some Companies Still Struggle to Improve Their Debt Recovery Rate? Many companies focus only on the final recovery rate and